Roof Condition & Home Appraisal Value | Expert Insights for Realtors
Welcome to the EliteAppraise.com blog, your definitive source for expert real estate valuation insights and market analysis. For real estate professionals—realtors, appraisers, and educators—understanding the nuances of a property’s physical condition is paramount. While many focus on kitchens and baths, one of the most significant factors influencing a home’s value, marketability, and even financeability is sitting right on top: the roof. This article breaks down precisely How Your Roof’s Condition Directly Impacts Home Appraisal Value, providing the data-driven perspective you need to advise clients, justify valuations, and stay ahead in a competitive market.
Key Takeaways
- First Impression & Overall Condition: Appraisers view the roof as a primary indicator of a property’s overall maintenance level. A neglected roof often signals other deferred maintenance issues.
- Remaining Economic Life: Valuation adjustments are tied directly to the roof’s “remaining economic life,” not just its current functionality. Age and material type are critical factors.
- Financing & Insurability: A roof in poor condition can make a property ineligible for FHA/VA loans and can cause significant insurance underwriting problems, shrinking the potential buyer pool.
- Cost-to-Cure Approach: Appraisers often use a “cost-to-cure” method, deducting the price of a necessary roof replacement from the property’s value.
- Marketability Impact: In current market trends, homes with newer roofs are significantly more attractive to buyers, often selling faster and for a higher price than comparable homes needing a new roof.
TL;DR
A roof’s condition is a critical factor in a home appraisal, directly influencing the final value through adjustments for its age, material, and remaining economic life. A poor roof can also limit buyer financing options and increase a home’s time on the market, making it a key point of analysis for real estate professionals.
An Appraiser Views the Roof’s Condition as a Direct Reflection of the Property’s Overall Maintenance and Care
The appraisal process begins long before an appraiser steps inside, with the initial view of the exterior setting the stage for the entire valuation. As one of the largest and most protective components of a home, the roof is a dominant feature that provides immediate clues about the property’s upkeep. A well-maintained roof suggests a diligent owner who likely cares for the rest of the home, while signs of neglect can trigger a more critical inspection of the entire property, from the foundation to the mechanical systems.
The “Halo Effect” of a Well-Maintained Roof
A clean, uniform roof with straight lines and no visible defects creates a powerful positive first impression. This “halo effect” can subconsciously influence an appraiser’s perception of the home’s other components. For realtors and their clients, this initial visual assessment signals that the home is likely “turnkey” and has been well-cared-for, justifying a stronger initial valuation. It communicates stability and a lack of immediate, costly projects for a potential buyer, which is a significant value proposition.
Red Flags: What Appraisers See in a Worn Roof
Experienced appraisers are trained to spot the subtle and not-so-subtle indicators of a roof nearing the end of its service life. These are not just cosmetic issues; they are data points that factor into the final value.
- Curling or Cupping Shingles: This is a clear sign of age and weather damage, indicating the shingles are losing their integrity and are susceptible to wind uplift.
- Missing Granules: The sandpaper-like granules on asphalt shingles protect them from UV rays. When they wear away, appearing as dark patches or accumulating in gutters, the shingle’s lifespan is drastically shortened.
- Dark Streaks or Moss: While often mistaken for dirt, dark streaks are typically caused by algae (Gloeocapsa magma). Moss growth can trap moisture against the roof surface, accelerating deterioration.
- Missing or Damaged Shingles: Obvious gaps in the roof are an immediate red flag for potential leaks and underlying water damage to the roof deck and attic.
These issues immediately prompt an appraiser to consider deferred maintenance in their overall condition rating on the Uniform Residential Appraisal Report (URAR). A property may be downgraded from a C3 (“Average”) to a C4 (“Fair”) or even C5 (“Poor”) condition, directly impacting which comparable sales are most appropriate and what adjustments are necessary.
Appraisers Directly Adjust a Home’s Value Based on the Roof’s Age and Remaining Economic Life, Not Just Its Current Functional State
A common misconception among homeowners is that if a roof isn’t actively leaking, it doesn’t negatively impact value. This is incorrect. Valuation professionals assess components based on their expected lifespan and contribution to value over time. A 20-year-old asphalt shingle roof, even if functional today, has little to no remaining economic life and will be treated as a significant near-future expense for the next owner, warranting a downward adjustment in the appraisal.
Defining “Economic Life” vs. “Physical Life”
Understanding these two terms is crucial for any real estate professional. They are not interchangeable, and appraisers focus on the former.
- Physical Life: The absolute total lifespan of a material before it completely fails. A shingle might physically remain on a roof for 35 years.
- Economic Life: The period over which a component, like a roof, contributes positively to the property’s value. This is typically the same as its warranted or expected lifespan. A 30-year architectural shingle has an economic life of 30 years. At year 25, even if it’s not leaking, it has very little economic life left to contribute to the home’s value.
The Calculation: Cost-to-Cure and Depreciation Adjustments
When a roof’s condition is a factor, appraisers use specific, defensible methods to calculate adjustments.
- Cost-to-Cure: This approach is used when a roof must be replaced for the home to be marketable or meet financing standards. The appraiser will obtain estimates for a full replacement and deduct that cost from the value derived from comparable sales. For example, if comparable sales indicate a value of $450,000 but the subject property needs a $15,000 roof, the appraiser may adjust the value down to $435,000. Deciding between a full replacement and a simple fix can be a tough call, and understanding the financial implications is key.
- Depreciation: For a roof that is simply old but still functional, an appraiser will calculate its depreciated value. Using an age-life method, a 15-year-old roof with a 30-year economic life is 50% depreciated. The appraiser then adjusts the subject property’s value against comparable properties that have newer roofs.
How Material Type Influences Valuation
The type of roofing material has a dramatic impact on economic life and, therefore, long-term value. Appraisers weigh this heavily when comparing properties.
| Roof Material | Typical Economic Life | Valuation Considerations |
|---|---|---|
| 3-Tab Asphalt Shingle | 15-20 Years | The baseline standard. Age is the primary factor; considered a significant liability after 15 years. |
| Architectural Shingle | 25-30 Years | A clear upgrade over 3-tab. Commands a higher value and has a longer period before depreciation becomes a major factor. |
| Metal / Standing Seam | 50+ Years | Higher initial cost but a much longer economic life. Age-related adjustments are minimal for decades. Valued for durability and low maintenance. |
| Slate / Clay Tile | 75-100+ Years | Often considered a “lifetime” roof. Condition and integrity of individual tiles are more important than age. High repair costs can be a factor. |
A Roof in Poor Condition Can Trigger Lender-Required Repairs or Even Make a Property Ineligible for Certain Types of Financing
For realtors, this is where a deal can quickly fall apart. The appraiser’s assessment of the roof directly impacts the lender’s willingness to fund the loan, as the property serves as their collateral. A compromised roof represents a significant risk to that collateral, and lenders will not ignore it.
Navigating FHA, VA, and Conventional Loan Requirements
Government-backed loans have particularly strict requirements because they are insuring the loan against default.
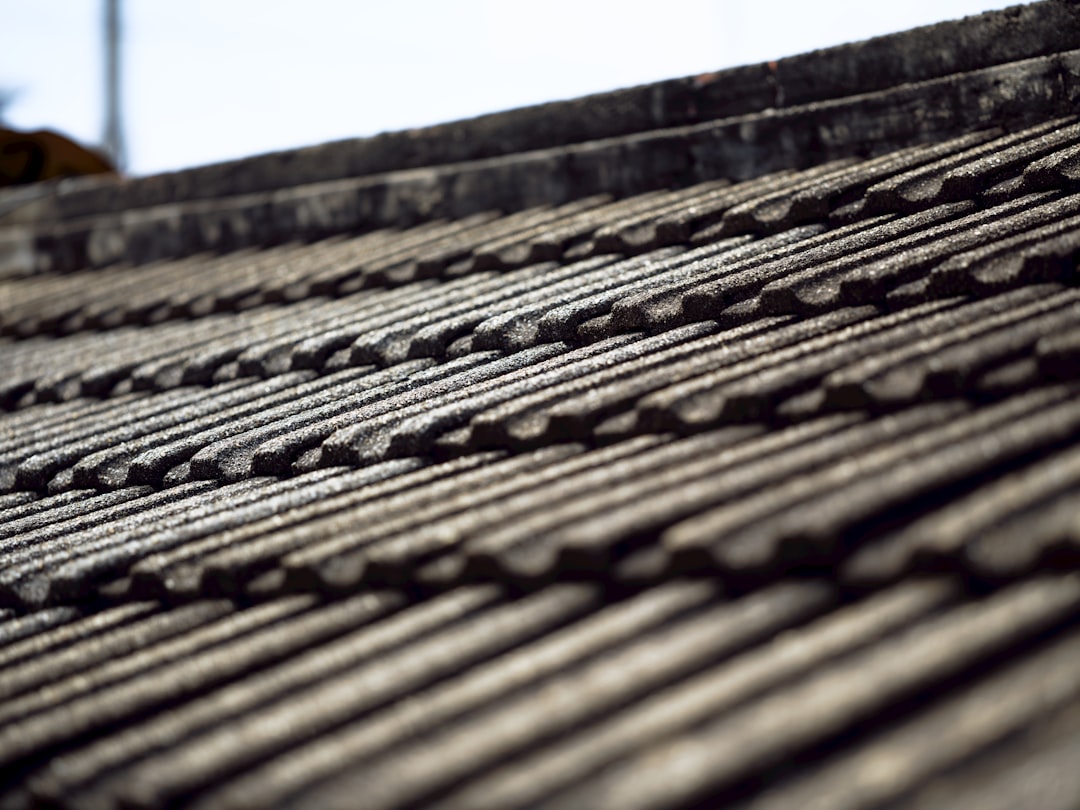
- FHA/VA Guidelines: The FHA and VA have minimum property standards that must be met. According to the HUD 4000.1 handbook, an FHA appraiser must certify that the roof is in good condition and has a remaining physical life of at least two years. If it shows any signs of needing repair or has less than two years of life remaining, the appraiser will make the appraisal “subject to” the roof being repaired or replaced before closing.
- Insurability Issues: This is a growing problem in many markets. A home with a roof older than 15-20 years may be difficult or impossible to insure. Since lenders require the buyer to obtain homeowner’s insurance before closing, a lack of insurability can kill a deal outright, regardless of the loan type.
The Impact on Your Buyer Pool and Negotiations
A home that is flagged for roof repairs immediately shrinks the potential buyer pool. Buyers using FHA or VA loans may be unable to proceed without the seller making costly repairs. Even conventional buyers without extra cash for an immediate roof replacement will be deterred. This reduction in demand often leads to longer days on market (DOM) and gives the remaining interested buyers significant leverage in negotiations, putting downward pressure on the final sale price.
Current Real Estate Market Trends Indicate That Buyers are Increasingly Factoring in the Immediate Cost of Major Repairs
In today’s information-rich market, buyers are more educated and risk-averse than ever. The prospect of a $15,000-$25,000+ roof replacement shortly after a major home purchase is a massive deterrent. This financial reality is something savvy real estate professionals must account for in their pricing and marketing strategies.
The Psychology of a “Turnkey” Property
Buyers are consistently willing to pay a premium for a truly move-in-ready home. A new roof is one of the most powerful marketing tools a seller can have, as it signals security, low maintenance, and no surprise expenses for years to come. This peace of mind translates directly into higher perceived value and a willingness to pay more. According to Remodeling’s 2023 Cost vs. Value Report, a new asphalt shingle roof can recoup over 61% of its cost in added home value, but its true benefit lies in enhanced marketability and financeability.
Data-Driven Impact on Comps and Market Time
When analyzing comparable sales, appraisers must look beyond square footage and location to the condition of major systems. A comp with a brand-new roof that sold for a premium helps establish the upward adjustment for a subject property with a similar feature. Conversely, a comp that sat on the market and sold for less due to an old roof provides the perfect data point to justify a downward adjustment. This direct, market-derived data is the foundation of a credible appraisal.
EliteAppraise.com Provides the Nuanced Data Needed to Accurately Value Properties with Roof-Related Issues
Staying ahead with expert real estate valuation insights is no longer a luxury—it’s a necessity. Understanding the complex interplay between a roof’s condition, material costs, market trends, and appraisal methodology is where EliteAppraise.com provides a distinct advantage to industry professionals. We empower you to move beyond guesswork and operate with data-driven confidence.
For Appraisers: Making Defensible Adjustments
Our platform provides access to localized cost data and deep market trend analysis, helping you make precise and well-supported “cost-to-cure” and depreciation adjustments for roofing. This granular data strengthens your reports, reduces the likelihood of challenges from underwriters, and ensures your valuations are accurate and defensible.
For Realtors: Pricing and Advising with Confidence
Leverage our insights to have informed, productive conversations with sellers about the real-world ROI of a roof replacement before listing. Use our data to accurately price a home with an older roof, setting realistic expectations from the start and avoiding appraisal-related setbacks that can jeopardize a transaction during the critical closing period. For a full scope of our resources, you can explore our comprehensive post sitemap, page sitemap, and category sitemap.
A Top-Down Approach to Accurate Valuation
The condition of a home’s roof is far more than an aesthetic detail; it is a fundamental component of its structural integrity, value, and marketability. From influencing an appraiser’s initial impression to dictating financing eligibility and impacting the final sales price, the roof’s effect is profound and multifaceted. By understanding how to assess its economic life, apply correct adjustments, and align with current market trends, real estate professionals can navigate transactions more smoothly, advise clients more effectively, and achieve more accurate outcomes.
Ready to elevate your valuation expertise? Explore the tools and insights at EliteAppraise.com to ensure your next appraisal or listing is built on a foundation of expert data.